DPA · FHA · VA · USDA · Conventional · Jumbo
Primary residence only

Homebuyers & down payment assistance

First home or fifth. No lender overlays, assistance programs with no first-time-buyer or income restriction, and a team that answers the phone.

Closes in as little as 14 days

Start application Book a consultation

Down payment assistance and these loan programs are for a home you will live in, not for investment property.

Program details

Down Payment Assistance

Up to 5% of the price toward down payment or closing costs. Options include a 5-year forgivable second, a 30-year repayable second, and closing-cost assistance. No first-time-buyer requirement. No income cap. Primary residence only.

Ideal for: Buyers with steady income and not much saved yet.

FHA

3.5% down, flexible credit, gift funds welcome. The workhorse for first-time buyers.

Ideal for: Credit scores in the 580–680 range or limited down payment.

VA

0% down, no monthly mortgage insurance, no loan limit for eligible borrowers.

Ideal for: Veterans, active duty, and eligible surviving spouses.

USDA

0% down in eligible rural and suburban areas — more of DFW's edges qualify than people expect.

Ideal for: Buyers looking outside the inner loop.

Conventional, High-Balance & Jumbo

From 3% down. Fixed or adjustable. High-balance and jumbo options for pricier homes.

Ideal for: Strong credit, any price point.

Refinance, HELOC & Reverse

Rate-and-term and cash-out refinance, home equity lines, and reverse mortgages for homeowners 62+.

Ideal for: Existing homeowners putting their equity to work.

← All programs

FHA vs. Conventional

Two of the most common ways to buy a home. They look similar until you read the fine print.

FHA
Conventional
Best for
Buyers with limited savings or a bumpier credit history
Buyers with solid credit who want flexibility down the road
Down payment
3.5%
From 3%
Credit
More forgiving
Stronger credit gets the best terms
Mortgage insurance
MIP, with an upfront charge plus a monthly charge
PMI, which can come off once you build enough equity
Speed
As little as 14 days
Watch out for
MIP can stick around for the life of the loan unless you refinance
A lower credit score can make PMI cost more
Our take: If your credit is strong, Conventional usually wins on long-term cost. If you need more breathing room on credit or savings, FHA gets you in the door.

All comparisons →

Forgivable vs. Repayable Down Payment Assistance

Assistance can be up to 5% of the price. The real question is whether you pay it back, and when.

5-year forgivable second
30-year repayable second
Best for
Buyers planning to stay at least five years
Buyers who may move or refinance sooner
How it works
A second loan that is forgiven over five years if you stay in the home
A second loan you pay back over 30 years
Cost to you
Nothing to repay if you stay the full term
You repay the full amount over time
Monthly payment
No extra monthly payment on the assistance
Adds a second payment each month
If you sell or refinance early
You may owe back part of it
Balance is paid off at sale or refinance
Watch out for
Leaving before year five
The extra monthly payment squeezing your budget
Our take: Staying put for five years? Forgivable is hard to beat. Not sure where you will be? Repayable keeps your options open at the cost of a second payment.

All comparisons →

HELOC vs. Cash-Out Refinance

Both turn home equity into cash. They just do it in very different ways.

HELOC
Cash-out refinance
Best for
Ongoing or uncertain expenses, like a phased remodel
One big, known expense
How you get the money
A line of credit you draw from as needed
A lump sum at closing
Your current mortgage
Stays exactly as it is
Gets replaced by a new loan
Payments
A second payment, usually adjustable
One new payment, usually fixed
Closing costs
Typically lighter
Typically heavier, like a full mortgage
Watch out for
A payment that can change over time
Giving up your existing loan terms
Our take: If your current mortgage terms are good, a HELOC lets you keep them. If you need a big lump sum and want a single payment, a cash-out refinance is cleaner.

All comparisons →

Common questions

How much do I need down?

FHA is 3.5% down, Conventional starts at 3%, and VA and USDA (eligible areas) are 0% down. The right one depends on your situation.

Do I have to be a first-time buyer to get down payment assistance?

No. There is no first-time-buyer requirement and no income cap. Assistance can be up to 5% of the price.

What kinds of down payment assistance exist?

A 5-year forgivable second, a 30-year repayable second, or closing-cost assistance. Which one fits depends on how long you plan to stay.

How fast can I close on a home?

As little as 14 days once you are under contract and the file is clean. Documents sent early make it faster.

What is the difference between pre-qualification and pre-approval?

Pre-qualification is a rough estimate from what you tell us. Pre-approval means we verified your documents, and that is the letter sellers take seriously.

Do you offer anything besides purchase loans?

Yes: jumbo and high-balance, refinance, HELOC, and reverse mortgages for homeowners 62 and older.
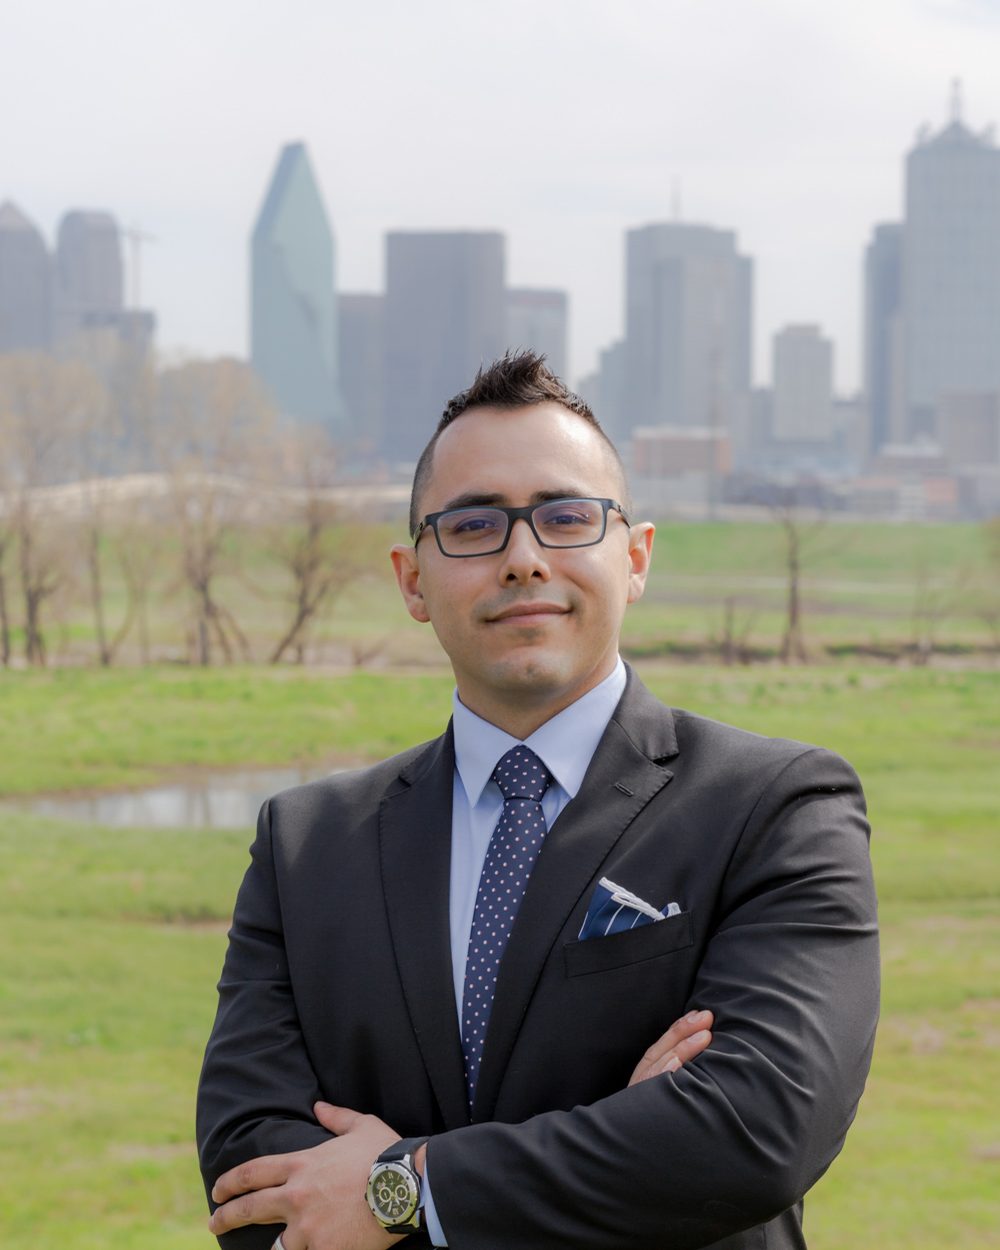
Néstor J. Caussade Morales

Founder · NMLS #1538512 · 13+ years

Néstor J. Caussade Morales

Mortgage Broker · DFW Mortgage Pros · Dallas–Fort Worth

“Speed isn’t a trick. It’s what happens when you underwrite the deal instead of the paperwork.”

Néstor has spent 13 years in Texas lending and business. He specializes in investor loans — fix & flip, ground-up construction and bridge — and in getting homebuyers in the door with little or nothing down.

He grew up in foster care. Today he runs a mortgage team in Dallas–Fort Worth, and when he isn't closing loans you'll find him on a dance floor.

  • Fix & Flip
  • Ground-Up Construction
  • Bridge
  • DSCR
  • Down Payment Assistance
  • ITIN
  • Foreign National
  • English · Español · ASL
More about Nestor →

Private consultation

Ready when you are.

Pre-qualify in 5–10 minutes by text, or pick a time and we'll call you.