Find your fit

FHA vs. Conventional

Two of the most common ways to buy a home. They look similar until you read the fine print.

FHA
Conventional
Best for
Buyers with limited savings or a bumpier credit history
Buyers with solid credit who want flexibility down the road
Down payment
3.5%
From 3%
Credit
More forgiving
Stronger credit gets the best terms
Mortgage insurance
MIP, with an upfront charge plus a monthly charge
PMI, which can come off once you build enough equity
Speed
As little as 14 days
Watch out for
MIP can stick around for the life of the loan unless you refinance
A lower credit score can make PMI cost more
Our take: If your credit is strong, Conventional usually wins on long-term cost. If you need more breathing room on credit or savings, FHA gets you in the door.
See what I qualify for Homebuyers & down payment assistance

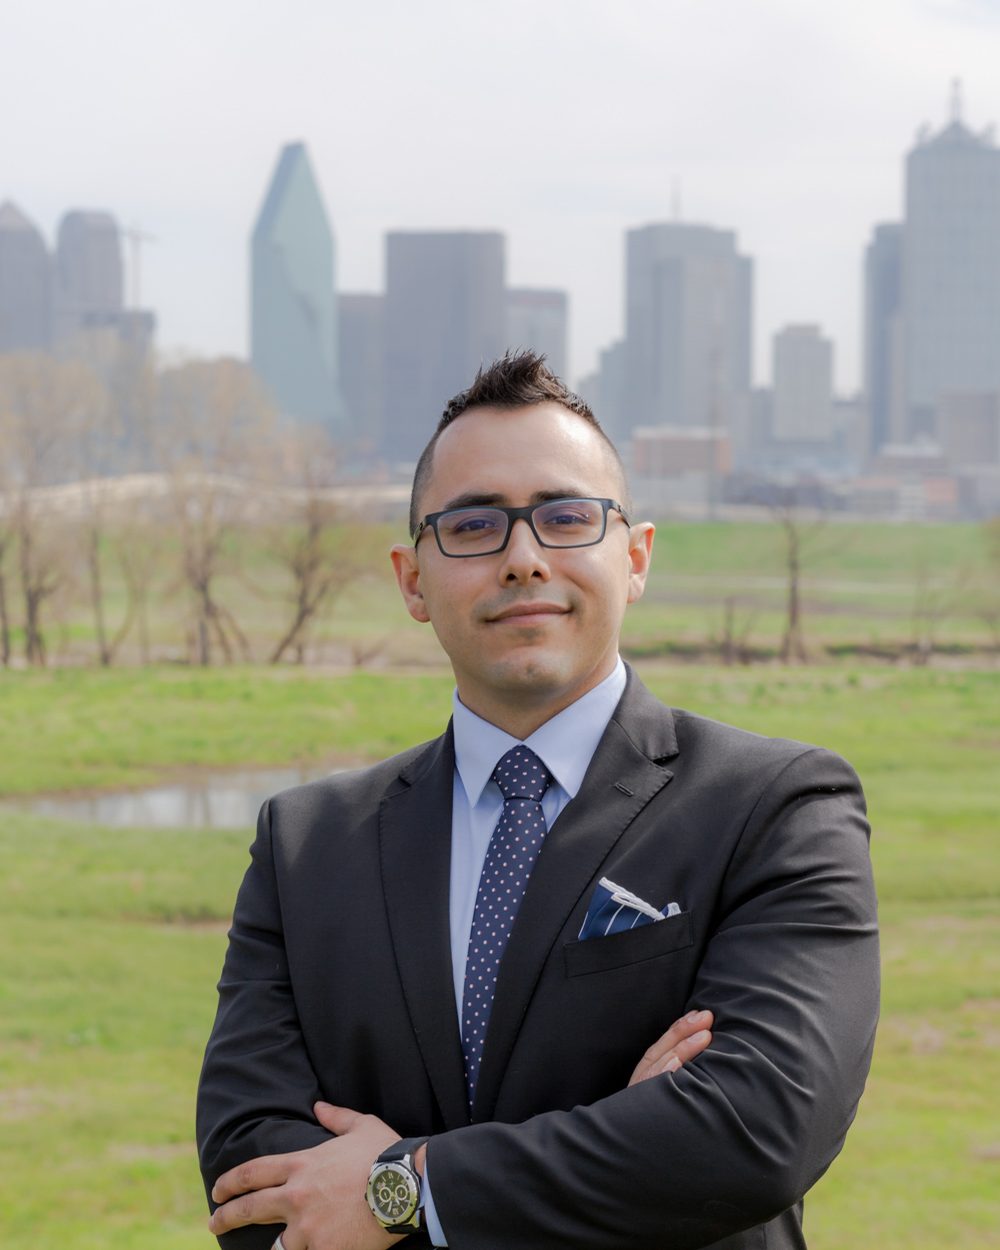
Néstor J. Caussade Morales

Founder · NMLS #1538512 · 13+ years

Néstor J. Caussade Morales

Mortgage Broker · DFW Mortgage Pros · Dallas–Fort Worth

“Speed isn’t a trick. It’s what happens when you underwrite the deal instead of the paperwork.”

Néstor has spent 13 years in Texas lending and business. He specializes in investor loans — fix & flip, ground-up construction and bridge — and in getting homebuyers in the door with little or nothing down.

He grew up in foster care. Today he runs a mortgage team in Dallas–Fort Worth, and when he isn't closing loans you'll find him on a dance floor.

  • Fix & Flip
  • Ground-Up Construction
  • Bridge
  • DSCR
  • Down Payment Assistance
  • ITIN
  • Foreign National
  • English · Español · ASL
More about Nestor →

Private consultation

Ready when you are.

Pre-qualify in 5–10 minutes by text, or pick a time and we'll call you.