Find your fit

Bank Statement vs. ITIN Loans

Both are for people who do not fit the standard W-2 box. They solve different problems.

Bank Statement
ITIN
Best for
Self-employed borrowers whose deposits tell the story better than tax returns
Borrowers who file with an ITIN instead of a Social Security number
Down payment
10%
3.5%
Credit
FICO from 640
Built around the credit file you have
Documentation
12 to 24 months of bank deposits, or a CPA-prepared P&L
ITIN-based file, with co-signer options
Loan size and term
Up to $3.5M
Terms up to 40 years
Watch out for
Messy or mixed personal and business accounts
A longer term means lower payments but more total interest over time
Our take: They answer different questions: how do I prove my income, and how do I qualify without an SSN. Some borrowers need to ask both, so tell me your situation.

See what I qualify for Self-employed, ITIN & foreign national
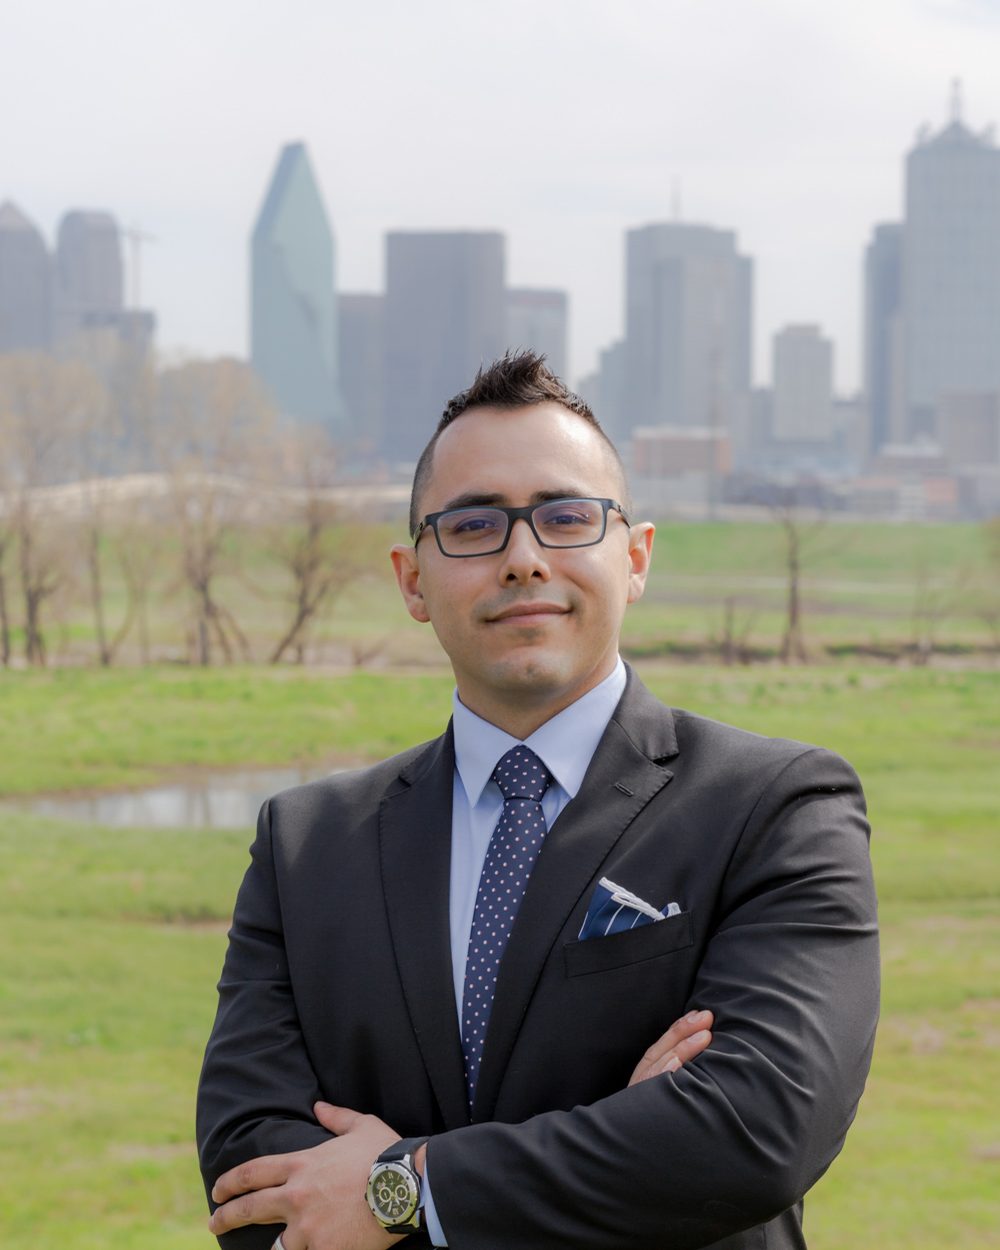
Néstor J. Caussade Morales

Founder · NMLS #1538512 · 13+ years

Néstor J. Caussade Morales

Mortgage Broker · DFW Mortgage Pros · Dallas–Fort Worth

“Speed isn’t a trick. It’s what happens when you underwrite the deal instead of the paperwork.”

Néstor has spent 13 years in Texas lending and business. He specializes in investor loans — fix & flip, ground-up construction and bridge — and in getting homebuyers in the door with little or nothing down.

He grew up in foster care. Today he runs a mortgage team in Dallas–Fort Worth, and when he isn't closing loans you'll find him on a dance floor.

  • Fix & Flip
  • Ground-Up Construction
  • Bridge
  • DSCR
  • Down Payment Assistance
  • ITIN
  • Foreign National
  • English · Español · ASL
More about Nestor →

Private consultation

Ready when you are.

Pre-qualify in 5–10 minutes by text, or pick a time and we'll call you.