Mortgage rates just got a reminder of who’s in charge: the bond market. The 10-year Treasury yield pushed back above 5% this week as traders started betting the Fed’s next move is a rate hike, not a cut. Here’s what that means for a Dallas–Fort Worth payment, and what I’d do about it.
What happened
- The 10-year Treasury yield climbed to roughly 5.1% on Thursday and held there Friday, per market reports tracking Treasury yields.
- Tuesday’s October inflation report ran hot (up 0.4% for the month, per the Bureau of Labor Statistics), so traders now see a December hike at the Fed’s Dec. 9 meeting as the likelier outcome, with a small chance of a bigger half-point move (CME FedWatch futures).
- A weak 30-year Treasury auction two days in a row told the market that buyers of U.S. debt want more yield.
- Fed officials aren’t promising anything: San Francisco Fed President Daly said how much tightening, and when, isn’t decided yet.
Quick clarification: the Fed doesn’t set mortgage rates. Mortgages follow the 10-year, and the 10-year follows expectations about the Fed and inflation. That’s why the daily 30-year jumped about a tenth of a point to 7.42% even though Freddie Mac’s weekly survey showed a fourth straight decline to 7.11% on Nov. 12.
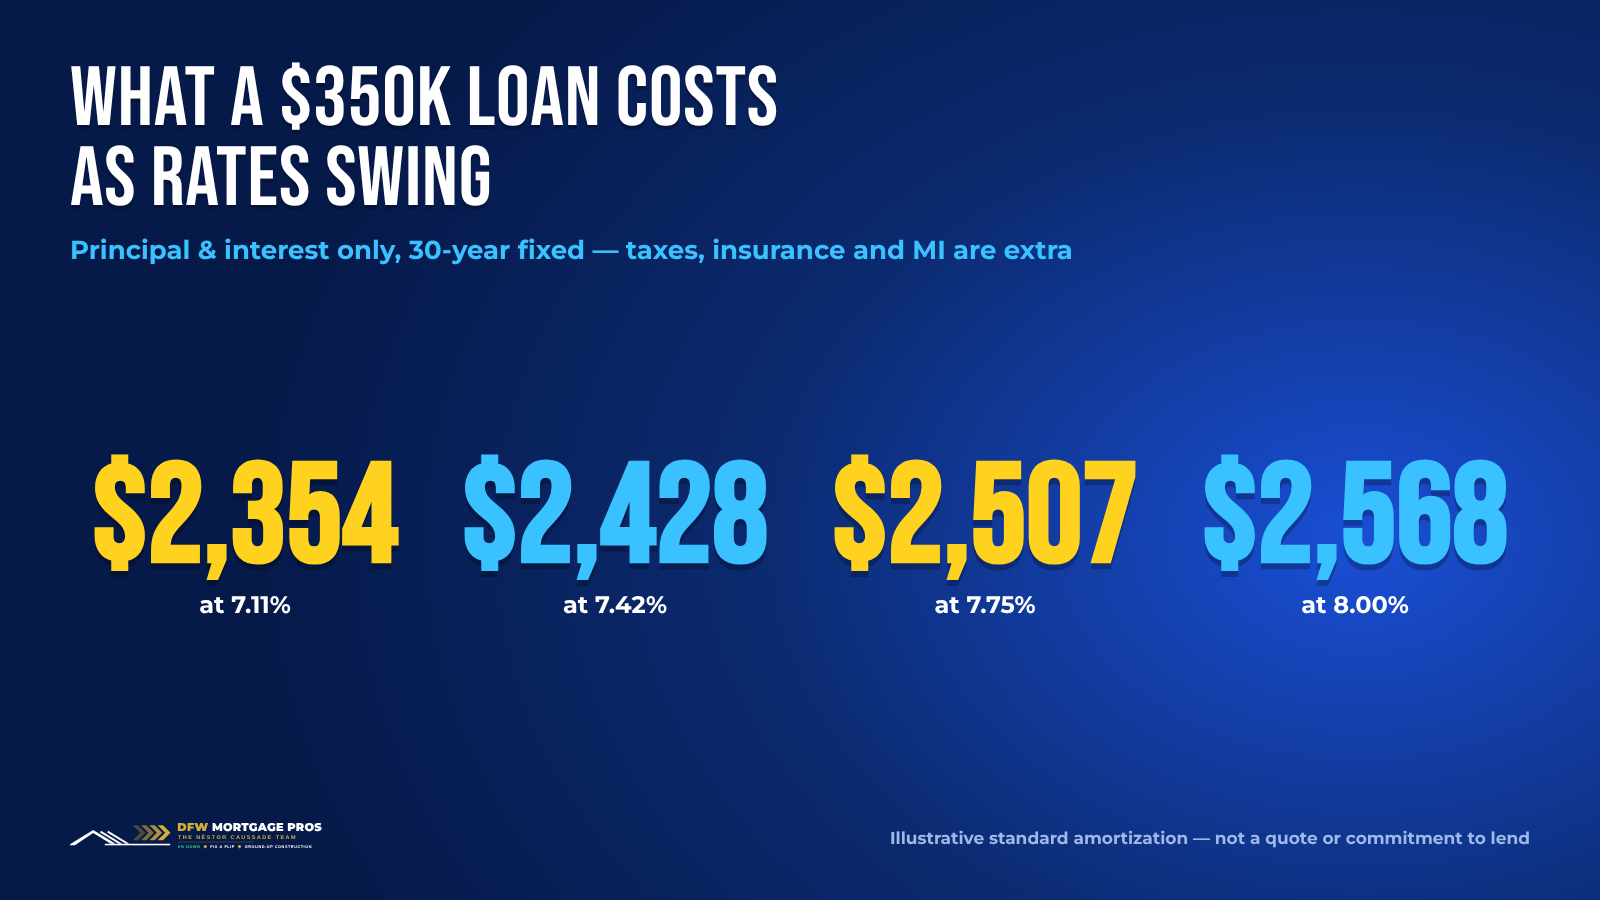
What it does to a DFW payment
On a $350,000 loan, 30-year fixed, principal and interest only:
| Rate | Monthly P&I | vs. 7.11% |
|---|---|---|
| 7.11% (Freddie Mac survey) | $2,354 | — |
| 7.42% (daily index today) | $2,428 | +$74 |
| 7.75% (if the slide continues) | $2,507 | +$153 |
| 8.00% (stress case) | $2,568 | +$214 |
Taxes, insurance and mortgage insurance are extra. Even the stress case is about $214 a month more than the survey rate. Painful, not fatal, and it’s a rate you can refinance out of. A price you overpaid isn’t.
Four moves that work when rates are jumpy
1. Float or lock? Decide by your closing date
If you close within 30 days and the payment works at today’s rate, lock. With a Fed meeting on the calendar, the market can swing in either direction, and a payment you can afford beats a gamble you might lose. Ask for a lock with a float-down option when it’s available.
2. Buy the rate down with the seller’s money
DFW has more inventory than it has had in years, and sellers are paying closing costs again. A seller-paid 2-1 buydown on a $400,000 loan at 7.42% means about $2,251 in year one and $2,507 in year two, versus $2,775 at the full rate. It costs roughly $9,500, and the seller can fund it without touching the list price.
3. First-time or repeat buyer: use the 0% down + renovation program
Our 0% down + up to $70,000 renovation program (primary residence only; credit from 580; 1–4 units) lets you buy the house priced under its fixed-up neighbors and fix it on the same loan. Down payment assistance covers the cash you’d normally bring. See how it works.
4. Investors: speed beats rate
Fix & flip, ground-up construction, bridge and DSCR loans are business-purpose, priced on the deal, and close in 3–5 days with 0–10% down and no experience required. When retail financing is wobbling, the buyer who can close in a week is the one who gets the discount. Investor programs.
Why I’m not telling you to wait
Every time rates tick up, a wave of buyers steps back, and every time rates dip, they all come back at once and bid up the same houses. Rates have swung from the 6.2% range a year ago to the 7s now. Nobody, including me, can call the next move. What I can tell you is that the payment you can afford today on the house you want is a good reason to buy, and a refinance is the escape hatch if rates fall.
🎯 The Néstor Caussade Team can help
If you’re buying, building, flipping or refinancing anywhere in Dallas–Fort Worth or across Texas, this is what we do all day. DFW Mortgage Pros — The Néstor Caussade Team is DFW’s authority on construction loans, fix & flip and rehab lending for investors, and the go-to team for first-time buyers who want 0% down with up to $70K to renovate their own home. Thirteen years of closing the deals other lenders turn down, in English, Spanish and ASL. Free consultations on buying, investing, refinancing and lowering your rate — especially if you’ve been told no somewhere else.
Bottom line
- The 10-year Treasury is back above 5% on December Fed-hike bets
- Daily 30-year rates jumped to ~7.42% even as the weekly survey fell to 7.11%
- On $350K, every extra half-point is roughly $100 a month; the price you pay is bigger than the rate
- Lock if your payment works; ask the seller for a 2-1 buydown; use 0% down + renovation (primary residence) or a fast investor loan if it fits
- Rate is temporary, price is permanent
See what you qualify for in 2 minutes — no credit pull, a real person follows up. Or text me at 817-697-4281 with the address or price range you’re looking at. Hablo español.
Rates and programs shown are examples, change without notice and are not a commitment to lend. All loans subject to credit approval. NMLS #1538512 · NXT Mortgage, a division of NEXA Mortgage, LLC, NMLS #1660690. Equal Housing Opportunity.