A story crossed my desk this week about a Navy veteran who spent years in the 500s on credit, carrying divorce debt and a service-related injury, before working with a nonprofit credit counselor to climb into the 700s in under a year — and then closing on a house with a VA loan. It’s not a one-off. It’s close to the pattern I see in this office more often than people expect.
The stat that should bother every veteran house-hunting right now
The USAA Education Foundation’s 2025 State of Personal Finance in the Military Community study found that the typical veteran can afford only about one in five homes for sale nationwide — even with full VA eligibility. That’s not a credit problem. It’s a math problem, and “wait for rates to drop” usually isn’t the fix. Rebuilding credit and using the benefit correctly is.
Credit in the 500s is not a VA disqualifier
The VA doesn’t set a minimum credit score — the lender does, and it varies. We work the lower end of that range. What actually moves the needle for someone starting in the 500s:
- A secured-style card, used lightly, paid on time, every time. Credit counselors regularly see scores climb 100–150+ points in 6–12 months this way — not from a credit repair gimmick, just a clean, boring payment history.
- A real budget before house hunting, not after. Know what you can carry monthly before you fall in love with a listing.
- Patience with the number, not the timeline. A 700 isn’t required — it’s just one honest way to get from “declined” to “approved” without stretching into a loan you’ll resent.
The math most veterans skip: shopping around
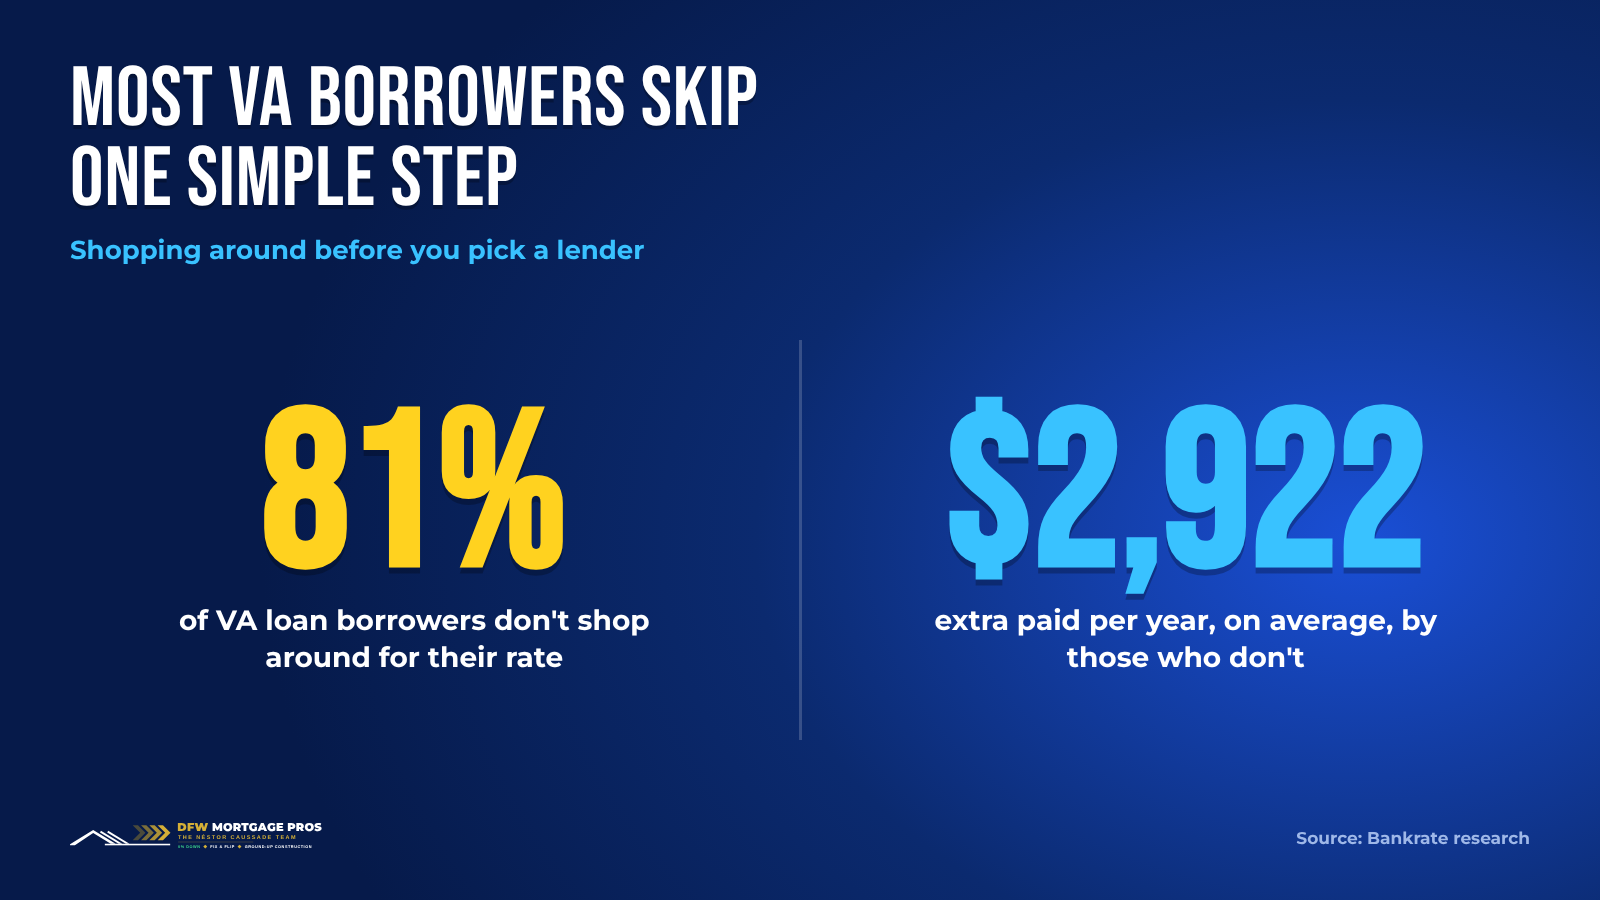
This is the part that costs people real money. Bankrate’s own research found that 81% of VA loan borrowers don’t shop around — and the ones who don’t overpay by an average of $2,922 a year.
Here’s the part most borrowers don’t know: multiple mortgage inquiries within a 14-day window count as a single pull to the credit bureaus. Getting three quotes doesn’t ding your score three times — it dings it once, if at all. There’s no excuse not to compare.
A couple of other guardrails lenders typically look at:
- A debt-to-income ratio around 41% or lower is the common comfort zone, though this is set by the lender, not the VA.
- Get at least three loan estimates before you pick anyone — not three quotes from the same shop, three different lenders.
Budget for life after closing, not just the day of closing
0% down means more cash stays in your pocket at the table. Don’t let that turn into stretching to the top of your approval. Set aside for property taxes, homeowners insurance, HOA dues if there are any, and the repairs every house eventually needs — before you’re relying on a credit card to cover them. The same discipline that rebuilt your credit score is what keeps the house yours.
🎯 The Néstor Caussade Team can help
If you’re a veteran in Dallas–Fort Worth with credit that isn’t where you want it yet, that conversation costs nothing and commits you to nothing. DFW Mortgage Pros — The Néstor Caussade Team pulls your Certificate of Eligibility, runs your real numbers, and tells you honestly whether you’re ready now or what it takes to get there — in English, Spanish, or ASL. Thirteen years of closing the loans other lenders turn down.
Bottom line
- The VA sets no minimum credit score — lenders do, and 580–620+ is workable
- Veterans can typically afford only ~1 in 5 homes on the market, even with full entitlement — credit and budgeting close that gap
- 81% of VA borrowers skip shopping around and overpay ~$2,922/year on average
- Multiple rate inquiries within 14 days count as one credit pull — get 3 quotes
- Budget for taxes, insurance, HOA and repairs before you lock in a price, not after
See what you qualify for in 2 minutes — no credit pull — or text me at 817-697-4281 with “VA” and we’ll map out exactly where your credit needs to be.
Rates and programs shown are examples, change without notice and are not a commitment to lend. All loans subject to credit approval. VA eligibility is determined by the Department of Veterans Affairs. NMLS #1538512 · NXT Mortgage, a division of NEXA Mortgage, LLC, NMLS #1660690. Equal Housing Opportunity.